Table of Contents
Why does an investor make irrational decisions despite having the information?
Have you ever bought a stock simply because you saw its price constantly rising? Or sold a good investment because you couldn’t bear to see your portfolio turn red?
You may have had a good financial analysis, but you couldn’t stick to it when the market moved against your expectations.
These actions are not just random mistakes, but are related to an important field in economics and investment known as behavioral finance .
Behavioral finance studies how emotions, psychological biases, and behavioral patterns influence financial decisions, and why investors do not always behave in the rational way assumed by traditional economic models.
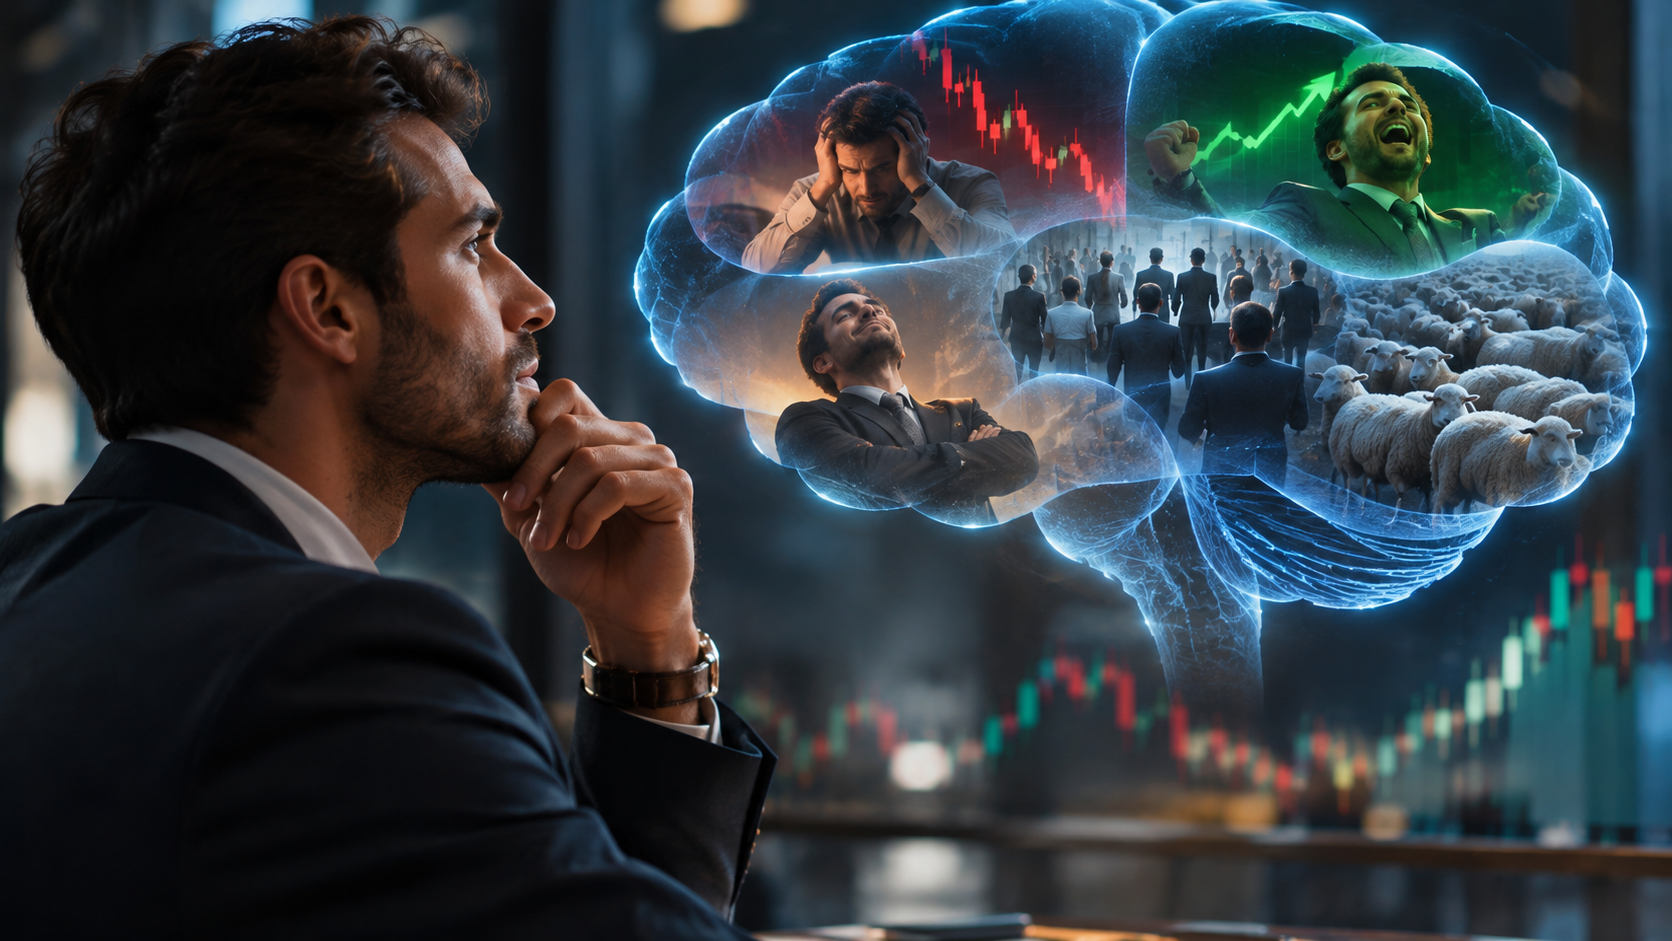
To understand this area, let’s start with four behaviors that can significantly influence investors’ decisions.
1. Loss Aversion
Why do we feel more pain from losing $1,000 than from making a profit of $1,000?
This is the essence of the concept of loss aversion.
Humans tend to feel that loss has a greater impact than gain of equal value. In other words, losing a certain amount of money can be more psychologically painful than the happiness we feel when we gain the same amount.
Imagine that you bought a stock for $100, and after a while its price dropped to $70.
You are now facing a 30% loss, but instead of reassessing the company and seeing if its fundamentals have changed, you decide to hold onto the stock because you don’t want to admit the loss.
You tell yourself: I’ll sell it when it goes back to $100.
The problem is that you made the original purchase price the basis on which you built your decision, even though the market does not care about the price at which you bought.
Even worse, you might quickly sell another winning stock just to secure the profit, while holding onto the losing stock for too long in the hope of a recovery.
This behavior may lead to an illogical outcome: holding onto weak investments and selling good investments prematurely.
The investment rule: Don’t ask yourself how to avoid admitting a loss, but ask yourself: If I owned this stock in cash today, would I buy it at the current price based on the company’s fundamentals and value?
2. Investor Overconfidence
Do you think you are better than most investors at picking stocks and predicting market direction?
That may be true, but the problem is that many investors think the same thing!
Overconfidence means that the investor overestimates his abilities, knowledge, and the accuracy of his predictions.
An investor might analyze five companies, make a profit from three of them, and then begin to believe that he has an exceptional ability to choose stocks.
But he may overlook the fact that the success of some of his investments may have been a result of general market conditions, and not necessarily his analytical skills.
One of the consequences of excessive confidence is:
- Trading frequently without necessity.
- Reducing the chances of error.
- Overestimating expected returns.
- Not giving enough attention to the risks.
- Building a portfolio that is too concentrated.
Imagine an investor who achieves a 40% return on a technology stock in one year. He then decides to increase the size of his investment position several times over, believing that he has understood the sector and is now able to predict its movements.
But past success does not necessarily prove the existence of exceptional skill, and the market conditions that helped him in the past may not continue in the future.
The investment rule: Don’t measure your skill solely by the number of winning trades. Evaluate the quality of your decisions, the risks you took, and your performance against a relevant benchmark over a sufficient period of time.
3. Herd behavior (Herding)
Imagine that a certain stock started to rise significantly, then the news and social media started talking about it, and everyone expected it to continue rising.
You suddenly find yourself thinking about buying it, not because you analyzed the company, but because you see a large number of investors buying it.
This is herding behavior, which means the tendency of individuals to imitate the decisions of others rather than relying on their own independent analysis.
This happens for multiple psychological reasons, including fear of missing out (FOMO), the desire to belong to the group, and the belief that others have better information.
But the problem is that a large number of buyers does not necessarily mean that the stock is undervalued.
Everyone may be excited about an excellent company, but its price has already risen to a level that reflects very high growth expectations.
The opposite can also happen; when investors start selling out of fear, others follow suit, and the wave of selling turns into greater pressure on prices.
The investment rule: Don’t let an investment’s popularity be a guarantee of its quality. Separate what the market thinks from what the financial data proves.
4. Information Cascades
This concept is close to herd behavior, but it is more profound.
In herd behavior, an investor imitates others due to a desire to belong or a fear of going against them.
In information chains, an investor may follow the decisions of others because he believes they have better information than he does, even if his own personal information points in a different direction.
Let’s say there’s a stock of a company you don’t know much about. You see a large investor buy the stock, then you see another investment firm enter the same position, and then a large number of investors start buying.
You conclude that these investors probably know something you don’t, so you decide to buy with them.
Then another investor comes along and observes your decisions and the decisions of others, and repeats the same behavior.
This creates a chain of decisions in which each investor relies on the decisions of those who came before him, instead of relying on independent information.
The problem is that the initial decision may be based on incomplete information, or even a mistake. However, this information may then spread through a long chain of decisions.
This may sometimes explain why the prices of some assets move strongly even though the available basic information does not justify the size of the movement.
The investment rule: Don’t assume that the investor who bought before you has better information than you. Try to get to the source of the decision and understand the economic and financial reasons behind it.
5. How can individuals’ decisions be irrational and markets relatively efficient?
Here we come to one of the most interesting ideas in behavioral finance.
If investors are making all these psychological mistakes, how can financial markets be effective in reflecting the information available within prices?
The answer is that the market is not a single investor, but a huge group of participants who have different information, goals, and expectations.
Imagine that a company’s stock is trading at $50.
Some investors believe the company is undervalued, so they buy the stock. Others believe it is overvalued, so they sell. And some investors don’t have a clear opinion, so they stay out of the market.
All these decisions interact with each other through supply and demand.
Even if some investors are acting out of fear or greed, there are other participants who analyze financial data, compare prices to fair values, and take advantage of mispricing opportunities when they see them.
Moreover, irrational investor decisions may sometimes conflict with each other, and do not necessarily lead to a continuous deviation in prices.
But this doesn’t mean the market corrects all errors immediately or that prices always accurately reflect intrinsic value. Some imbalances can persist for extended periods and become more pronounced when psychological biases coalesce in one direction.
Therefore, irrational behavior at the individual level can coexist with a degree of efficiency at the market level as a whole, but that does not make the market immune to errors or bubbles.
Why should an investor understand behavioral finance?
Because the investor is not only dealing with numbers, but also with himself.
You may learn to analyze financial statements, value companies using discounted cash flows, calculate return on capital, and compare price to intrinsic value.
But all these tools can lose their usefulness if you allow fear to make you sell at the worst possible time, or overconfidence to push you to take risks you don’t understand, or herd behavior to make you buy an asset simply because everyone else is buying it.
Behavioral finance does not ask you to stop feeling fear or excitement; this is a natural part of human nature.
Rather, it helps you recognize these feelings and understand their impact, so that they do not turn into ill-considered investment decisions.
The biggest challenge for an investor may be their own mind.
Financial markets are full of information, analysis, and opportunities, but having access to information does not necessarily mean being able to make the right decision.
A fear of loss may make you cling to a weak investment, overconfidence may make you underestimate risk, herd behavior may drive you to buy what everyone else is buying, while information chains may make you follow other people’s decisions without understanding their reasons.
Therefore, it is not enough to learn how to analyze companies and determine their fair value. You must also learn how to analyze your own decisions.
A good investor not only tries to understand the market, but also tries to understand himself.