A busy week in global markets: Tech giants earnings, the Fed meeting, and inflation data under scrutiny.
US markets are gearing up for an eventful week, with earnings announcements from several of the world’s largest technology companies, including Alphabet, Microsoft and Amazon, coinciding with the US Federal Reserve meeting to decide on interest rates, and the release of inflation data that may provide new signals about the direction of monetary policy and the future of financial markets.
These developments come at a time when investors are assessing the strength of US corporate earnings and their ability to sustain growth, particularly in the technology sector, which is seeing massive investments in artificial intelligence. Meanwhile, US monetary policy remains a key factor influencing stock and bond movements and financial asset valuations. Attention is particularly focused on the earnings reports of major technology companies, which will give investors an opportunity to evaluate whether the huge investments in AI infrastructure are beginning to translate into tangible revenue and profit growth, or whether these investments continue to strain cash flow and capital expenditure.
Three of the largest companies in the “Big Seven” technology group—Alphabet (Google’s parent company), Microsoft, and Amazon—are preparing to announce their quarterly results this week, one of the most anticipated events of the current earnings season. Alphabet and Microsoft are scheduled to release their results on Wednesday after the close of the US market, while Amazon will announce its results on Thursday.
As for Microsoft, forecasts indicate earnings per share of $4.72, with expected revenues of $90.75 billion.
Regarding Amazon, markets expect earnings per share of $1.96 and revenues of $202.2 billion for the same quarter. These results will be a crucial test of the three companies’ ability to maintain high growth rates, especially given the growing questions about the economic return on their massive investments in artificial intelligence and whether these investments will support future profits rather than increase spending pressures.
Among the other technology companies preparing to announce their results this week is Intel, whose performance is being closely watched by investors amid increasing competition in the semiconductor industry and developments related to demand for processors and artificial intelligence infrastructure. Analysts predict that Intel may achieve earnings per share of $0.40, with revenues reaching $16.47 billion.
The company’s results will provide important indicators regarding the performance of the semiconductor sector, the extent to which it has benefited from the expansion of global technology spending, and Intel’s ability to improve its financial results in the face of competition within the processor market.
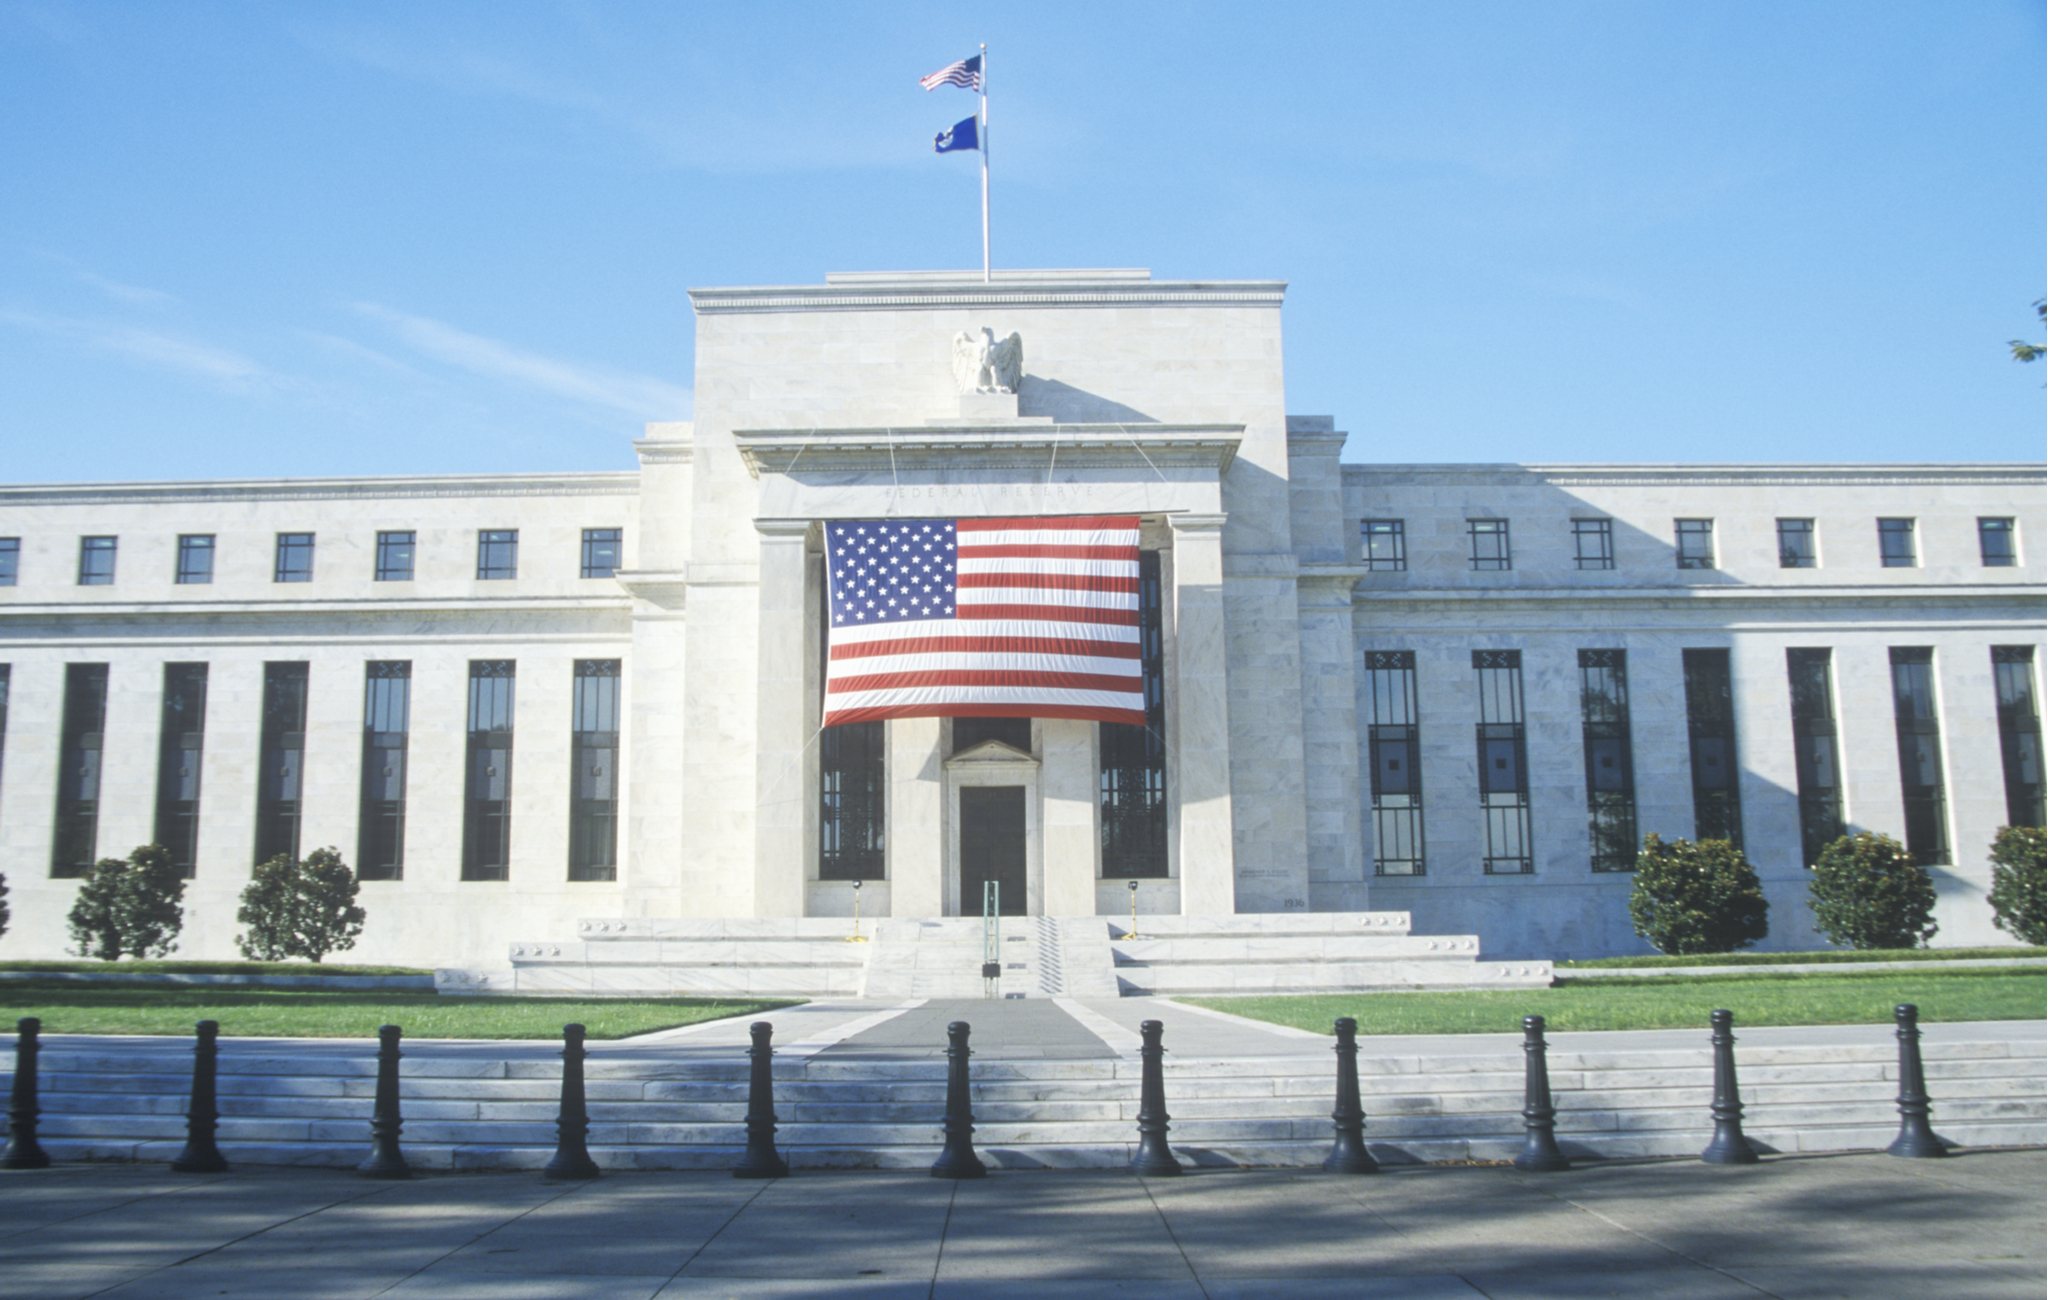
On the other hand, investors are awaiting the meeting of the Federal Open Market Committee (FOMC) of the US Federal Reserve, which begins Tuesday and lasts for two days, with the monetary policy decision expected on Wednesday. Expectations are that the US central bank will keep its benchmark interest rates unchanged at a range of 3.75% to 4%, following a 25-basis-point increase at its September meeting.
According to data from the CME FedWatch tool, the probability of interest rates remaining unchanged at the current meeting is around 90%, reflecting market expectations that the Federal Reserve will maintain its current monetary policy pending further economic data. The meeting comes at a time when assessing the relationship between inflation and economic activity is becoming increasingly important, as investors seek to determine whether price pressures will allow the US central bank to begin easing monetary policy in the near future, or whether persistently high inflation will prompt it to keep interest rates at their current levels for an extended period.
The meeting’s significance extends beyond the decision itself to encompass the messages Federal Reserve officials might convey regarding the future of interest rates and their willingness to continue monetary easing or maintain a more restrictive policy should economic conditions warrant it. In the bond markets, the iShares 20+ Year Treasury Bond ETF, which tracks the performance of long-term U.S. Treasury bonds, declined by 0.05% in after-hours trading on Friday.
The iShares 7-10 Year Treasury Bond ETF, which tracks medium-term US bonds, also fell by 0.04%, in limited moves reflecting investors’ anticipation of the Fed’s decision and expected economic developments.
Concurrently with the Federal Reserve meeting, attention is focused on the US Personal Consumption Expenditures (PCE) report, the central bank’s preferred inflation gauge, due for release on Thursday. This data is particularly significant as it will provide a fresh perspective on inflationary pressures during September and the extent to which price increases will persist, potentially influencing monetary policy decisions in the coming period.
These figures are among the important indicators that the Federal Reserve relies on to assess the direction of inflation, especially since the core index helps to measure more sustainable price pressures away from the fluctuations resulting from energy and food prices.
Any reading higher than expected would increase pressure on the US Federal Reserve and prompt investors to reassess the likelihood of interest rate cuts in the near future, while lower-than-expected data might give markets more room to be optimistic about monetary easing.
Also on Thursday morning, the latest weekly jobless claims data is expected to be released, providing further insight into the state of the US labor market. Initial jobless claims fell to 194,000 last week, near their lowest level in almost 57 years. This comes as investors monitor the labor market’s ability to maintain its strength amidst persistent inflationary pressures, with the balance between job growth and rising prices being a key factor influencing the Federal Reserve’s decisions.
The continued low unemployment claims may reflect a strong labor market, but they could also raise questions about the persistence of pressure on wages and demand, making the new data highly anticipated this week. US stocks are awaiting corporate earnings and the Federal Reserve’s decision. Regarding market performance, major US index funds posted modest gains in after-hours trading on Friday.
The SPDR S&P 500 ETF, which tracks the performance of the S&P 500 index, rose by 0.15%. The Invesco QQQ Trust ETF, which tracks the Nasdaq 100 index, climbed by 0.07%, while the SPDR Dow Jones Industrial Average ETF Trust, linked to the Dow Jones Industrial Average, gained 0.13%.
Despite these limited gains, data from Stocktwits showed that retail investor sentiment toward the S&P 500 was in extremely bearish territory at the time of the report. This reflects the cautious sentiment prevailing among investors ahead of a week packed with earnings reports from major technology companies, the US monetary policy decision, and inflation and labor market data.
Beyond the major technology companies, the week will see the release of earnings reports from a large number of American companies operating in various sectors, giving investors a broader picture of the performance of the US economy and trends in spending and demand. Among the most prominent companies expected to announce their results this week are Robinhood, Reddit, and Boeing, along with the telecommunications companies T-Mobile and Verizon.
This diversity allows investors to assess the performance of the technology, telecommunications, energy, pharmaceutical and various industries sectors, at a time when monitoring operating profits and management’s expectations for future periods is becoming increasingly important.
While investors wait to see if technology companies can deliver tangible returns from their AI investments, inflation and labor market data will provide important signals about the future of US interest rates.