Table of Contents
Global financial markets saw an improvement in risk appetite during Wednesday’s trading, following the results of the US midterm elections which resulted in the Democratic Party gaining control of both houses of Congress.
Despite the Democrats winning both houses of the US Congress, the risk of renewed military conflict between the United States and Iran remains.
Today’s market optimism appears to stem from expectations that the likelihood of escalation will decrease following Trump’s loss of support in Congress. However, this optimism may be exaggerated, as the new Congress will not assume its powers until January 2027.
Therefore, caution remains necessary, as markets may experience sharp fluctuations in the coming days depending on military and political developments between Washington and Tehran.
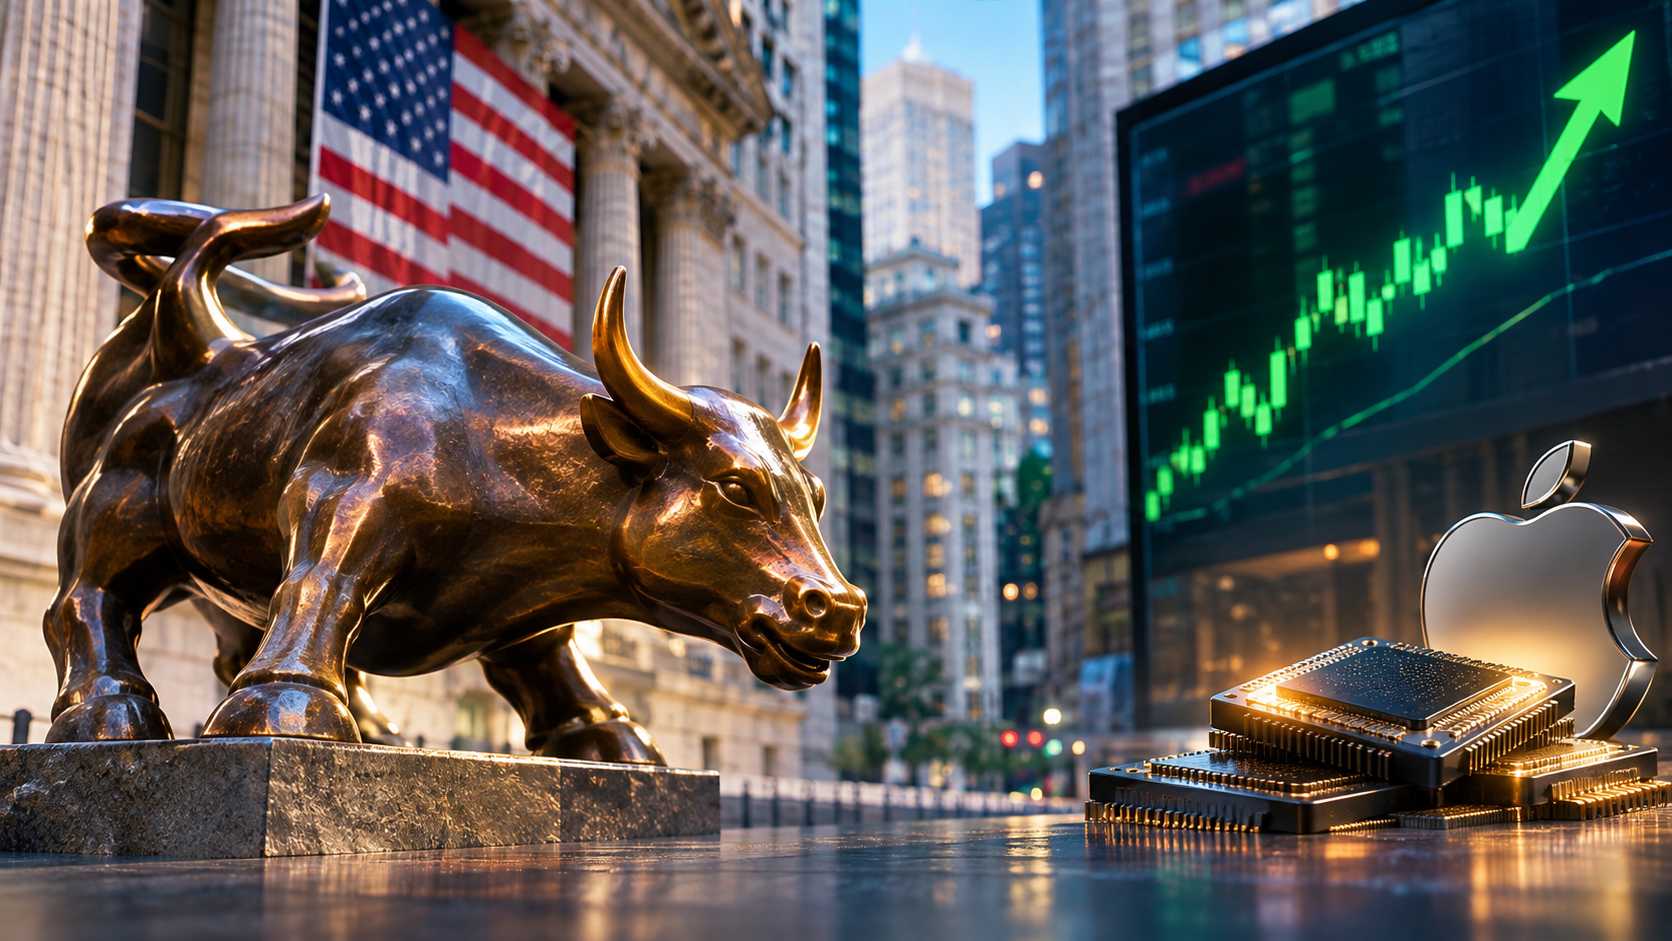
US futures and European stocks rose, while the dollar weakened, helping to support gold and silver prices.
The results from AMD and Arista Networks have also reinforced confidence in the continued demand for AI infrastructure.
First: US markets
Tuesday, November 3rd closures
| Index | Closure | Change |
|---|---|---|
| Dow Jones | 51,786.72 | −0.38% |
| S&P 500 | 7,568.92 | +0.36% |
| Nasdaq Composite | 25,372.01 | +0.83% |
| Russell 2000 | 2,812.45 | +0.20% |
US markets ended Tuesday’s session with a mixed performance, as technology and semiconductor stocks recovered.
Nvidia’s stock rose by about 3%, while the Philadelphia Semiconductor Index climbed by about 3%, indicating improved demand for the sector’s stocks.
US Futures – Wednesday
Around 11:35 AM Saudi time.
| Index | Change |
|---|---|
| Dow Jones Futures | +1.44% |
| S&P 500 Futures | +1.04% |
| Nasdaq Futures | +0.93% |
Futures contracts point to expectations of a positive opening for US markets, supported by improved risk appetite following the election results.
The Wall Street session begins at 5:30 PM Saudi time.
Second: European markets
Readings during Wednesday’s session
| Index | Level or change |
|---|---|
| STOXX Europe 600 | +1.40% |
| FTSE 100 (British) | 10,764.49 points |
| Italy FTSE | +1.18% |
European stocks rose, supported by the banking and mining sectors, as global sentiment improved and the dollar weakened.
Gold mining companies also benefited from the strong rise in precious metal prices.
Third: Asian markets
Wednesday, November 4th session
| Index | Change |
|---|---|
| Nikkei 225 Japanese | −1.42% |
| Korean KOSPI | +0.62% |
| Shanghai Composite (Chinese) | +2.16% |
Asian markets recorded a mixed performance, with Japanese stocks declining under pressure from technology, while Chinese and Korean stocks rose.
Fourth: Oil, gold, silver, and currencies
| origin | the price | Change |
|---|---|---|
| Brent crude | $101.68 | −1.85% |
| WTI crude | $94.34 | −1.82% |
| Instant gold | $4,046.74 | +3.00% |
| Instant silver | $52.13 | +4.80% |
| GBP/USD | 1.3495 | +0.63% |
Gold: Prices rose, supported by a decline in the dollar and US bond yields, and increased investment demand for precious metals.
Silver: It made stronger gains than gold, benefiting from improved investment demand and higher metal prices.
Oil: Prices fell as fears of an imminent US military escalation against Iran eased, despite continued geopolitical tensions.
The dollar came under selling pressure after the US election results, while major currencies performed better against it.
Fifth: Key economic and geopolitical news
US midterm elections
The elections resulted in the Democratic Party gaining control of both the House of Representatives and the Senate.
Markets are monitoring the implications of the results for economic policies and regulatory legislation, especially those related to technology and artificial intelligence companies.
The clarity of the political outcomes contributed to an improved appetite for risk during Wednesday’s trading.
US-Iranian tensions
Oil prices fell as expectations of a new military escalation in the near term diminished.
But negotiations still face disagreements, even as diplomatic efforts continue.
Energy markets remain sensitive to any developments affecting supplies and shipping traffic in the Gulf.
Sixth: Results of major American companies
AMD – Q3 2026 Results
| Financial indicator | Result |
|---|---|
| Revenue | $13.4 billion |
| Annual revenue growth | +45% |
| Adjusted earnings per share | $2.09 |
| Data center revenues | $8.55 billion |
| Data center revenue growth | +97% |
| Fourth quarter revenue forecast | Approximately $17 billion |
AMD announced strong results, driven by high demand for AI processors and data centers.
The company’s stock rose by more than 6% in extended trading following the announcement, boosting confidence in continued spending on artificial intelligence infrastructure.
Arista Networks – Q3 2026 Results
| Financial indicator | Result |
|---|---|
| Revenue | $3.66 billion |
| Annual revenue growth | +58.5% |
| Adjusted earnings per share | $1.20 |
| Earnings per share forecast | $1.08 |
| Fourth quarter revenue forecast | $3.9–4.0 billion |
The company exceeded profit and revenue expectations, benefiting from increased demand for networking equipment used in artificial intelligence data centers.
The company’s stock rose by about 12% in extended trading following the results.
The results indicate that the processor, network, and infrastructure sectors continue to benefit from the expansion of investments in artificial intelligence.
Seventh: Key data and upcoming events
Thursday, November 5
- The Bank of England’s monetary policy decision.
Friday, November 6
- US Non-Farm Payrolls Report for October.
The jobs data is of particular importance in determining expectations for US monetary policy during the December meeting.
Eighth: Monetary and Bond Policy
Yields on 10-year US Treasury bonds fell to around 4.92%
The decline in returns contributed to supporting gold and stock prices.
But expectations of continued tight monetary policy remain, amid concerns about inflation and energy prices.
Markets are awaiting US jobs data to assess the likelihood of interest rate changes in the coming period.